To ensure you receive the best service possible,
please enter your zip code below:




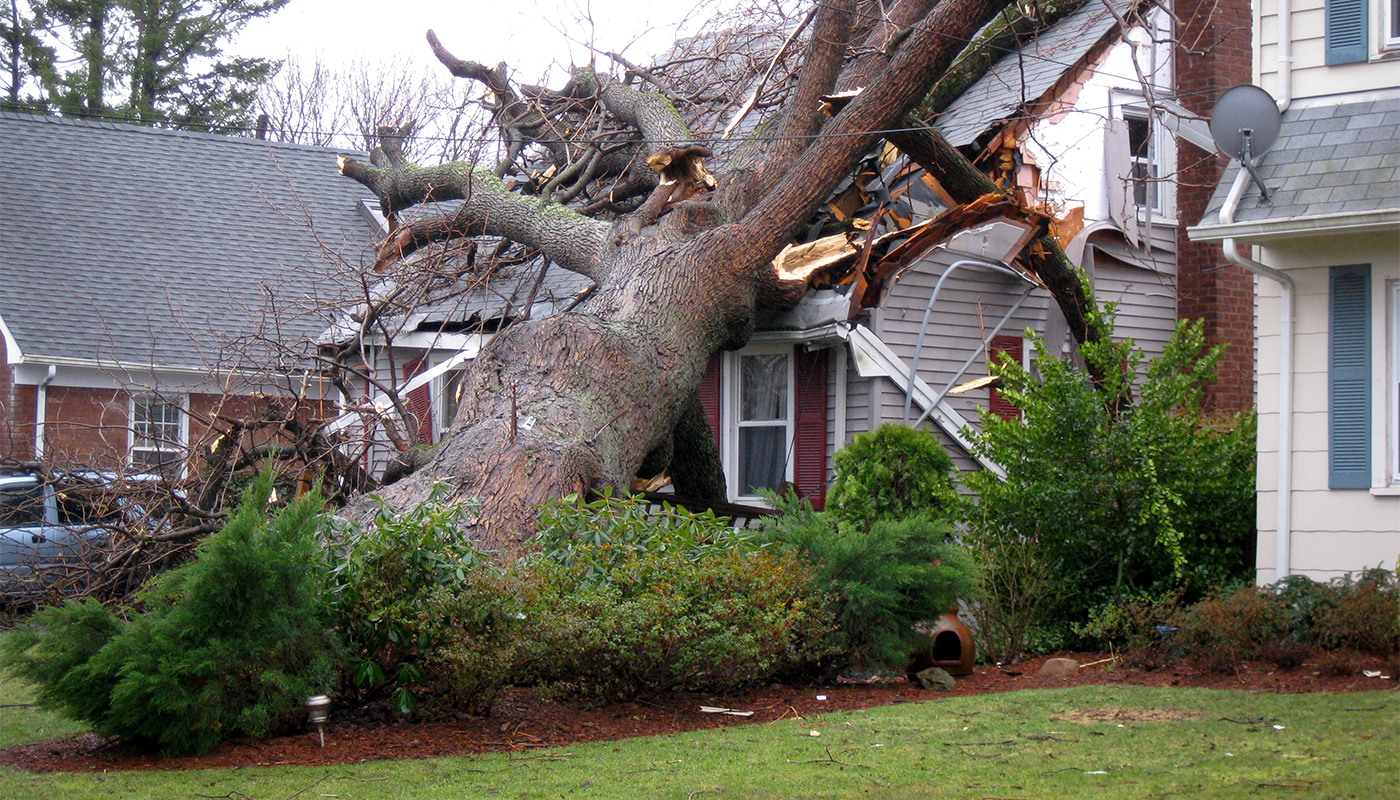
Quick answer: If a tree falls on your parked car, comprehensive auto insurance generally helps pay to repair or replace the vehicle, minus your deductible. Liability-only coverage typically does not cover fallen tree damage. If the tree was dead, neglected or dropped by a contractor, another party’s liability insurance may also come into play.
surprises happen – good and bad
A fallen tree can create an expensive repair bill. It’s always a good time to review whether comprehensive coverage is part of your auto policy.

You’re about to run some errands, head outside and stop short: a tree has fallen on your parked car. A fallen tree can do a lot of damage, from a cracked windshield to deep dents, and in the worst case, total the vehicle. Your first thought is probably, “Now what?”
What you do next depends on the type of car insurance coverage you carry. Comprehensive coverage generally pays for damage related to a fallen tree, minus your deductible. In this case, liability coverage alone may leave you paying out of pocket.
Here’s what to do next and how to understand whether your auto insurance may help.

Put safety first. Check whether anyone was near the car and look for injuries. If anyone is hurt, call 911 to get them help.
A downed tree often happens after a storm, so make sure the area is clear of other hazards, such as downed power lines or live wires. If you see any downed power lines, don’t approach the car or tree, and contact your local police and fire department.
Don’t forget to check on other tree limbs. They may not be stable. Look up as well, since a second limb may be hanging and ready to fall.

Once the area is safe, start building your record. Thorough documentation helps keep a claim moving, so capture more than you think you need.
It depends on your coverage and who's responsible for the tree. Here are a few scenarios.
As part of a full coverage auto insurance policy, comprehensive helps pay to repair or replace your vehicle minus your deductible. For example, if you have a $1,000 deductible and the damage is $4,000, you pay $1,000, and your insurer likely will cover the remaining $3,000.
If the vehicle is declared a total loss because repairs would cost more than the car is worth, your insurer generally pays out its actual cash value. If the car is worth $17,000, they’ll cover up to $16,000, minus your $1,000 deductible.
In this case, you’ll likely have to pay for damages out of pocket. A liability-only policy won’t cover fallen trees, and collision insurance only covers damage from hitting something while driving.
Even if a neighbor’s tree falls on your car, your comprehensive coverage usually handles the claim. You’ll still want to file a claim.
If the tree has been an issue and it’s been reported to your neighbor and they did nothing, they may be held responsible, and their homeowners’ insurance might cover your deductible.
Third party contractors or companies that cause damage to your vehicle while pruning or removing trees, if insured, their liability insurance should cover the damage.
Whenever another party is involved, get their insurance details and pass them on to your agent.

Storm-related tree damage can change a few things.

While a falling tree often isn’t in your control, a few precautions can help lower the risk.
A fallen tree can damage your car and your wallet. Comprehensive coverage helps add another layer of protection.
A fallen tree can damage your car and your wallet. Comprehensive coverage helps add another layer of protection, especially if you regularly park outdoors or live in an area with mature trees, seasonal storms or high winds. Review your policy now so you understand your deductible, coverage limits and what to do if a claim is needed.
surprises happen – good and bad
A fallen tree can create an expensive repair bill. It’s always a good time to review whether comprehensive coverage is part of your auto policy.
Yes, if you have comprehensive coverage. Comprehensive auto insurance generally helps pay for damage caused by falling objects, including trees and branches, minus your deductible.
Usually no. Liability coverage generally pays for damage you cause to others, not damage to your own vehicle from a fallen tree.
Your comprehensive coverage will often handle the claim. If the neighbor knew the tree was dead, diseased or dangerous and did not address it, their homeowners insurance or liability coverage may be involved.
Tree removal depends on where the tree fell, what was damaged and what your policy covers. Auto insurance may focus on vehicle damage, while homeowners insurance may apply if the tree also damages the home or blocks a driveway.
Only move the car if it is safe to do so and there are no hazards such as downed wires, unstable limbs or structural damage. Take photos and videos first and contact your insurer or agent for guidance.
This information is being provided for general informational purposes only. The Auto Club Group does not assume any liability in connection with providing this information.